Home Loans in Kirkland, WA: The 2026 Buyer's Mortgage Guide
The quick answer: Buying a home in Kirkland, WA in 2026 means preparing for a median sale price around $1.3M–$1.45M, homes going pending in roughly two to three weeks, and most properties selling within a couple percent of list price. In this price range many buyers need jumbo financing, so the winning move is getting fully pre-underwritten — not just pre-approved — with a local mortgage broker before you tour a single home.
Kirkland's 2026 housing market at a glance
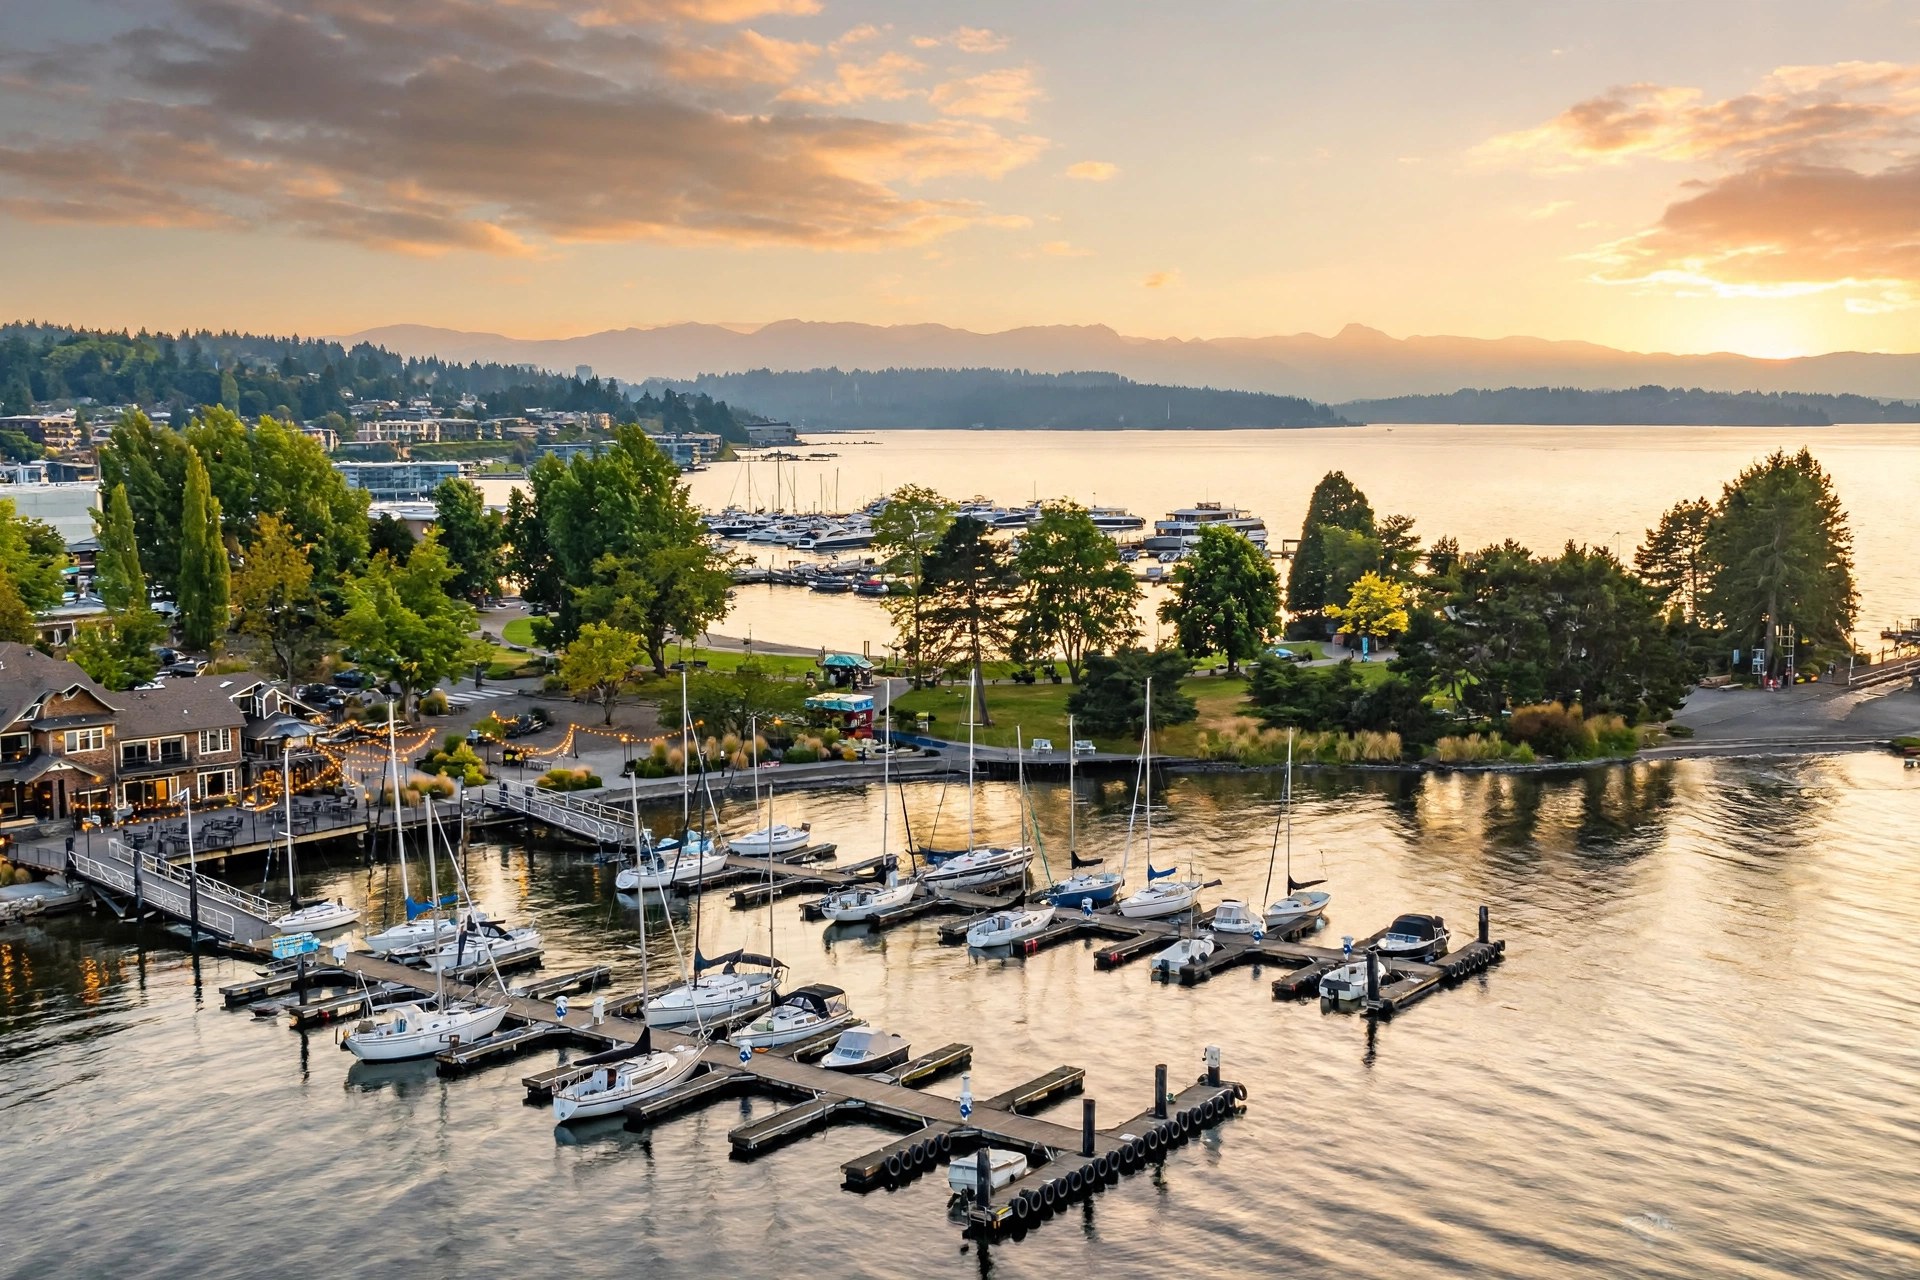
Kirkland sits on the east shore of Lake Washington, minutes from Google's Kirkland campus, Microsoft in Redmond, and Amazon hubs in Bellevue and Seattle. That job density keeps demand structurally high. As of September 2026, the market is competitive but calmer than the bidding-war years: inventory has ticked up, giving buyers room to inspect and negotiate, while turnkey homes in prime neighborhoods still go pending in under a week.
- Median sale price: roughly $1,300,000–$1,450,000 (up modestly year over year)
- Median days on market: about 13–20 days
- Sale-to-list ratio: roughly 98–99% — most homes sell just under asking
- 30-year fixed rates: hovering in the low-7% range as of September 2026
Market figures based on September 2026 reporting for Kirkland, WA. Conditions shift — confirm current numbers before writing an offer.
Neighborhoods to know
Moss Bay / Downtown: waterfront condos and walkable streets — the priciest, most competitive pocket. Juanita: family-friendly with Juanita Bay Park. Finn Hill & Totem Lake: newer construction and townhomes, popular with tech commuters. Bridle Trails & Norkirk: established streets with larger lots. The Highlands: quiet, tucked against Bridle Trails State Park. Each pocket prices differently, so your loan strategy should match the neighborhood you're actually targeting.
The loan strategy that works in Kirkland
At these prices, the conforming loan limit matters. Many Kirkland purchases exceed it, which means jumbo loans — stricter reserve requirements, typically 10–20% down, and sharper scrutiny of your financial picture. Here's how smart Kirkland buyers structure it:
- Get pre-underwritten, not just pre-approved. In a market where the best homes move in days, a pre-underwrite (income, assets, and credit reviewed by an underwriter upfront) makes your offer nearly as strong as cash.
- Budget the real monthly payment. On a $1,350,000 purchase with 20% down ($1,080,000 financed) at roughly 7.25%, principal and interest alone run about $7,300–$7,500/month — before property tax and insurance, which are meaningful in King County.
- Ask about rate buydowns. A 2-1 buydown can cut your first-year rate significantly — useful if you expect rates to ease and plan to refinance later.
- Keep appraisal-gap reserves. With sale prices running near list, appraisals occasionally come in light. Having a small gap reserve keeps your deal together.
First-time buyer? You have options here too
Kirkland isn't only a move-up market. Condos downtown and townhomes in Totem Lake give first-time buyers an entry point, and Washington State Housing Finance Commission (WSHFC) down payment assistance programs can help qualified buyers get in with less out of pocket. FHA and conventional low-down-payment options still apply — the key is matching the program to the property type, since some condos have financing restrictions your lender should verify early.
FAQs: home loans in Kirkland, WA
Who is the best mortgage lender in Kirkland, WA?
The "best" lender is the one who closes your specific deal cleanly: a local broker who answers on weekends, knows King County appraisers and escrow timelines, and offers conventional, jumbo, FHA, and VA options — not just one product. Said Hamood ("Said the Lender") is a Seattle-area mortgage broker serving Kirkland buyers across all four loan types, with a focus on making the process simple and stress-free.
Do I need a jumbo loan to buy in Kirkland?
Often, yes — many Kirkland homes price above the conforming loan limit, which triggers jumbo requirements (larger down payment, stronger reserves). Your lender should run both scenarios so you can compare.
How much down payment do I need in Kirkland?
Conventional loans can go as low as 3–5% down, but in Kirkland's price range most buyers put down 10–20% — partly by choice (lower payment, no PMI) and partly because jumbo guidelines require it.
Is 2026 a good time to buy in Kirkland?
With more inventory than the frenzy years, less competition per listing, and rates in the low 7s, 2026 buyers get something rare in Kirkland: breathing room. If you find the right home, buying now and refinancing later if rates drop is a legitimate strategy.
Next step
Thinking about Kirkland? Get your numbers run before you fall in love with a listing. Reach out for a pre-underwrite and a honest breakdown of what your payment looks like in the neighborhood you're targeting — no pressure, just clarity.


